

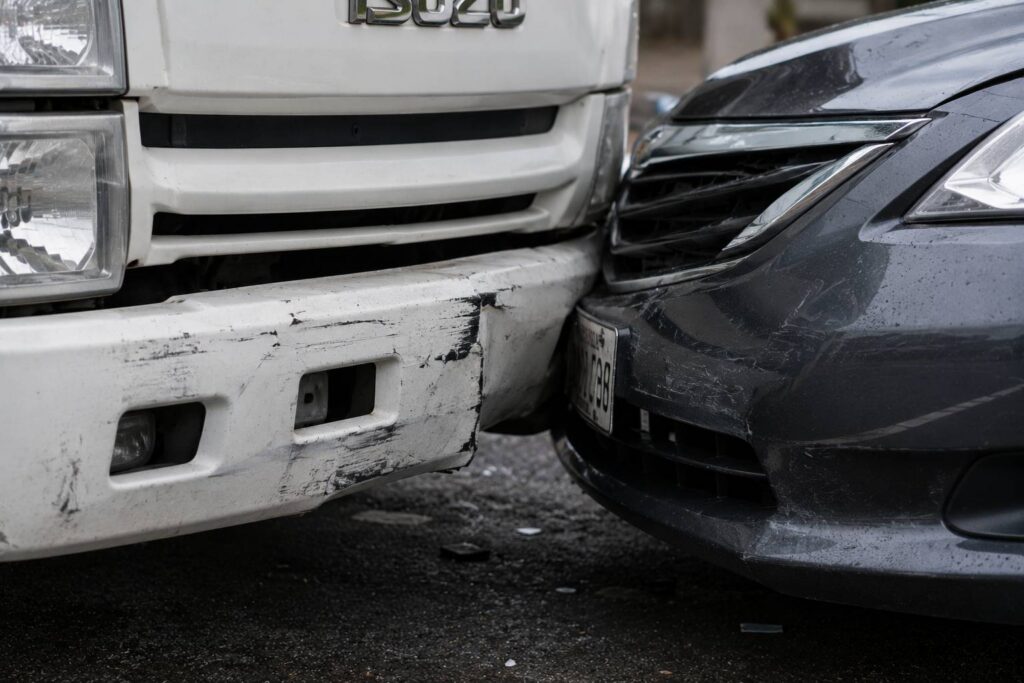
A hit-and-run collision is one of the most stressful experiences a driver can endure on Oahu roads. In the chaos following a sudden impact on a dark stretch of the H-1 or a busy Waikiki intersection, the at-fault driver speeds away, leaving the victim trapped in a damaged vehicle with mounting medical emergencies.
Under Hawaii law, fleeing the scene of an injury accident is a severe criminal offense. Haw. Rev. Stat. § 291C-12 classifies leaving the scene of a crash involving serious bodily injury or death as a Class B felony. Despite these strict penalties, hit-and-run crashes remain alarmingly common in Honolulu, often driven by panic, suspended licenses, lack of insurance, or driving under the influence.
For the victim left behind, a hit-and-run creates a massive legal and financial void. The primary source of recovery in any car accident is the at-fault driver’s bodily injury liability insurance. When the driver vanishes, that source of compensation disappears with them.
Fortunately, Hawaii auto insurance laws provide a specific safety net for these exact scenarios: Uninsured Motorist (UM) coverage. Navigating a UM claim, however, requires understanding strict statutory definitions, proving “physical contact,” and effectively treating your own insurance company as the opponent in a civil claim.
The Role of Uninsured Motorist (UM) Coverage in Hawaii
Under Haw. Rev. Stat. § 431:10C-301, all motor vehicle insurance companies in Hawaii must offer consumers the option to purchase Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage. While PIP (Personal Injury Protection) is mandatory and covers initial medical bills regardless of fault, UM coverage is optional.
However, Hawaii law dictates that UM coverage is automatically included in your policy unless you specifically rejected it in writing.
If you have UM coverage, your own insurance policy steps into the shoes of the hit-and-run driver. Your insurer becomes legally responsible for paying the damages you would have recovered from the fleeing driver, including surgery costs, ongoing rehabilitation, lost wages, and pain and suffering.
The Challenge of the UM Claim
Filing a UM claim fundamentally shifts your relationship with your insurance carrier. Instead of processing a standard claim, you are now demanding a high-value bodily injury settlement from your own company. Your insurer essentially takes on the role of the defense, scrutinizing your medical records, questioning the severity of your injuries, and looking for ways to minimize the payout.
The “Physical Contact” Requirement for Hit-and-Run Claims
One of the most complex hurdles in a Hawaii hit-and-run UM claim is the “physical contact” rule. Insurance companies aggressively defend against “phantom vehicle” claims—situations where a driver claims another car swerved into their lane, forcing them off the road and into a guardrail, but the two vehicles never actually touched.
To prevent fraudulent claims, Hawaii Administrative Rules generally require proof that the hit-and-run vehicle made actual physical contact with your vehicle (or your person, if you were a pedestrian or cyclist).
If a reckless driver cuts you off on the Pali Highway and you swerve into a ditch to avoid them, your insurance company will likely deny your UM claim based on a lack of physical contact.
Exceptions and Evidentiary Proof
Proving physical contact when the other car is gone requires immediate and thorough investigation. Our trial attorneys look for specific evidence to satisfy this legal requirement:
- Paint Transfer: Microscopic paint transfer on your bumper or side panels proves another vehicle struck yours.
- Property Damage Profiles: Specific dent patterns, shattered taillight plastic, and tire rubber marks on your vehicle’s body provide objective proof of an impact.
- Independent Eyewitness Testimony: Statements from other drivers on the road who witnessed the impact and saw the vehicle flee are crucial.
- Surveillance and Dashcam Footage: Video evidence from nearby businesses, municipal traffic cameras, or your own dashcam can definitively prove contact occurred.
Steps to Take Immediately After an Oahu Hit-and-Run
The moments following a hit-and-run are critical. Your actions dictate whether you can successfully pursue a UM claim.
1. Call 911 and Do Not Pursue
Never attempt to chase a fleeing driver. High-speed pursuits put your life and the lives of others at extreme risk, and the fleeing driver may be dangerous or intoxicated. Pull over safely, turn on your hazard lights, and dial 911 immediately.
2. File an Official Police Report
Under Hawaii law, a hit-and-run must be reported to the proper authorities within 24 hours to qualify for UM coverage in many policy agreements. The Honolulu Police Department report serves as the foundational document for your claim, verifying the time, location, and circumstances of the crash.
3. Document the Scene and Gather Witness Info
If you are physically able, take photos of your vehicle’s damage, specifically focusing on any paint transfer or impact marks. If other drivers stop to help, ask for their names and phone numbers immediately. Eyewitnesses are often the strongest evidence you have.
4. Seek Immediate Medical Evaluation
Even if you feel your injuries are minor, adrenaline masks severe trauma like whiplash, internal bleeding, and concussions. Go to the emergency room or an urgent care clinic immediately. Delaying treatment gives your insurance company grounds to argue your injuries were not caused by the crash.
Maximizing Your Recovery: Stacking UM Coverage
If your family owns multiple vehicles insured under the same policy in Hawaii, you may have the option to “stack” your UM coverage. Under Haw. Rev. Stat. § 431:10C-301(d), insurers must offer the option to stack UM and UIM coverage limits.
If you selected the stacking option and own two cars, each with $50,000 in UM coverage, your total available coverage for a single hit-and-run accident becomes $100,000. Stacking provides a vital financial lifeline when injuries require long-term care or specialized surgeries. Our legal team thoroughly reviews your policy declarations page to identify all available layers of coverage.
To understand how civil courts and insurance adjusters calculate the true value of your physical injuries, review our guide on What Compensation Can You Recover for a Hawaii Personal Injury Case?.
Frequently Asked Questions About Hit-and-Run Claims
Does filing a UM claim increase my insurance premiums?
Under Hawaii law, your insurance company cannot raise your premiums or cancel your policy simply because you filed an Uninsured Motorist claim for an accident where you were entirely not at fault (such as being rear-ended by a hit-and-run driver).
What if I was walking or biking when the hit-and-run occurred?
Your personal Uninsured Motorist coverage generally extends to protect you even if you are not inside your vehicle. If a hit-and-run driver strikes you while you are walking in a crosswalk or riding a bicycle, you can still file a UM claim against your own auto insurance policy.
Can I use my UM coverage if the police eventually catch the driver?
If HPD tracks down the hit-and-run driver, your claim shifts back to targeting their bodily injury liability insurance. However, if the arrested driver was driving without insurance—a common reason for fleeing the scene—your UM coverage remains your primary source of financial recovery.
How does my PIP coverage work with my UM claim?
Under Hawaii’s no-fault system, your Personal Injury Protection (PIP) pays your initial medical bills first. Your UM claim covers damages beyond what PIP pays, including excess medical bills, lost wages, and pain and suffering. Hawaii law, specifically Haw. Rev. Stat. § 431:10C-301.5, includes a “covered loss deductible” which prevents double recovery by reducing your UM settlement by the amount already paid out by your PIP benefits.
How long do I have to file a lawsuit against my own insurance company?
In Hawaii, the statute of limitations for filing a lawsuit based on a motor vehicle accident is generally two years from the date of the crash, or two years from the date of your last PIP payment. However, insurance policies often contain strict internal deadlines for reporting hit-and-run claims, sometimes within 24 to 30 days. Contacting a lawyer immediately protects your rights.
Protect Your Legal Rights: Contact Rosenberg Hoffman
If you survived a hit-and-run collision on Oahu, do not try to negotiate an Uninsured Motorist claim alone. Your insurance company will look for ways to dispute physical contact or minimize the severity of your injuries.
At Rosenberg Hoffman, our Honolulu-based personal injury lawyers have represented local drivers, commuters, and pedestrians since 1995. We manage all communication with your insurance carrier. We investigate the crash scene, secure forensic evidence of physical contact, and aggressively pursue the maximum UM limits available under your policy.
We provide dedicated legal representation across a complete range of personal injury categories. Whether your case involves an uninsured motorist, a catastrophic Car Accident, a severe Motorcycle Accident, or a collision involving Moped, Bicycle, and Pedestrian Accidents, our trial team knows how to win.
We also handle tragic cases requiring complex Wrongful Death litigation.
You will work directly with your trial attorney from start to finish. We operate on a strict contingency-fee basis. You pay absolutely zero upfront costs. We collect no legal fees unless we win a financial settlement or court judgment for you.
Call 808-470-4819 or visit https://rhlawhi.com/contact/ to schedule a free, 100% confidential consultation today.
